Thinking About Buying a Waterfront Home in St. Pete or the Beaches? What You Need to Know
There is something special about living on the water in St. Petersburg.
Maybe it's having your morning coffee while watching dolphins in Tampa Bay. Maybe it's the sunset over Boca Ciega Bay. Or maybe it's being able to walk out your back door, get on your boat and head out for the day.
But two homes can both be advertised as “waterfront” and offer completely different lifestyles.
Waterfront living can be fantastic. It simply comes with a different set of ownership considerations.
Before you fall in love with the view, it's important to understand exactly what you're buying.
First Question: Are You Buying the Water or the View?
When someone tells me they want a waterfront home, one of my first questions is what they actually want from the water.
For some buyers, it's all about the view. They want to sit outside and watch the sunrise over Tampa Bay or the sunset over the Gulf. Others want a peaceful canal, where they can watch the boats go by without being directly exposed to open water.
And for some, the view is secondary. What they really want is access to the water because they own a boat or plan to buy one.
Those are very different searches.
The direction a home faces matters, too. If you picture yourself having coffee outside every morning, you may prefer an eastern exposure. If your favorite part of the day is sitting outside with a glass of wine and watching the sunset, a western exposure might be more your style.
Neither is better. It depends on how you want to live.
If You Own a Boat, Not All Waterfront Is Equal
A beautiful waterfront home isn't necessarily the right waterfront home for your boat.
Before buying, we need to know what kind of boat you have, where you want to take it and whether the property can accommodate it.
Water depth is a major consideration, particularly at low tide. So is bridge clearance. A route that works perfectly for a small center-console boat may not work for a larger vessel with a fixed tower.
Then there's the question of access. How long will it take to reach Tampa Bay or the Gulf? Are you looking for protected water where you can keep your boat, or do you want quicker access to open water?
If the property has a dock or lift, we also need to establish whether it is suitable for your boat's size and weight.
These are things to investigate before you fall in love with the kitchen.
Look Beyond the House: The Seawall, Dock and Lift Matter, Too
When buying a waterfront home, the inspection shouldn't stop at the house.
A seawall, dock or boat lift can represent a significant future expense. I want buyers to understand the age and condition of those structures, what maintenance or repairs may be needed, and whether any proposed changes would require permits or other approvals.
For a property with a seawall, that may mean bringing in a qualified marine contractor or engineer. If there's a dock or lift, we should investigate its condition, capacity and permit history.
And don't assume that because a dock exists, you can automatically enlarge it, add a lift or change the shoreline however you wish. Depending on the property and the proposed work, local, state or federal requirements may apply.
The point isn't to make waterfront ownership sound complicated. It's to make sure you understand the entire property you're buying.
Waterfront Homes Can Cost More to Maintain
Salt air is hard on things.
Exterior metal components, railings, fixtures, fasteners and mechanical equipment may need more attention in a coastal environment. Even items that aren't part of the house, such as bicycles, outdoor furniture and vehicles, can require extra care when regularly exposed to salt spray.
Then add the potential maintenance of a seawall, dock, pilings or boat lift.
None of this means waterfront ownership isn't worth it. It means your maintenance budget should reflect the environment you're buying into.
The purchase price is only one part of the cost of living on the water.
Flood Risk Is Part of the Waterfront Conversation
Many waterfront properties in St. Pete and the beach communities are located in designated high-risk flood areas, although the designation and actual risk must be checked for each individual property.
And being on the water doesn't mean every property has the same exposure.
The location, elevation, construction and history of the home all matter. So does what happened during recent storms.
Hurricane Helene in 2024 was a particularly difficult reminder of that reality. Some homeowners who had lived in their properties for decades experienced flooding they had never seen before.
When I'm evaluating a waterfront home with a buyer, I want to look beyond the view and ask some very practical questions: What is the property's flood-zone designation? What is its elevation? Has it flooded before? What happened during Helene and Milton? Were repairs made afterward?
A home's history can provide useful context, but a history of not flooding is not a guarantee that it won't flood in the future.
Know the flood risk. And know your own tolerance for risk.
To research a property's mapped flood hazard, search online for FEMA Flood Map Service Center and enter the property address. A property's mapped designation is an important starting point, not a complete account of every possible flooding scenario.
The FEMA 50% Rule: What Waterfront Buyers Need to Understand
One of the biggest lessons to come out of the 2024 storms was how many homeowners were unfamiliar with the rules governing repairs to older homes in regulated flood hazard areas.
You've probably heard this referred to as the FEMA 50% rule.
Under the National Flood Insurance Program's minimum standard, a building in a Special Flood Hazard Area is considered substantially damaged when the cost to restore it to its pre-damage condition equals or exceeds 50% of the building's market value before the damage occurred.
Notice that I said building. The calculation does not include the value of the land, which can be substantial for a waterfront property.
There is a related concept called substantial improvement. It applies when the cost of certain improvements to an existing building reaches the applicable threshold. These rules can affect renovations even when a home hasn't suffered storm damage.
Here's the part buyers need to understand: The local jurisdiction enforces the applicable floodplain rules, and its requirements may be more restrictive than the federal minimum.
For example, Pinellas County uses a 49% threshold for properties in the unincorporated areas it administers. Properties within a city fall under that city's applicable regulations and permitting process.
When a building meets the applicable substantial-damage or substantial-improvement threshold, it generally must be brought into compliance with current floodplain requirements. Depending on the structure and circumstances, that could mean elevating the home or replacing it with a compliant structure. The exact options need to be confirmed with the jurisdiction responsible for the property.
Drive through our beach communities today and you can see some of the different ways homeowners responded to the storms. Some homes have been elevated. Others were demolished and replaced. Still others were repaired.
That last category deserves particular attention when you're considering a purchase.
Buying a Home That Flooded and Was Repaired? Investigate Its History
A beautifully renovated home can be very appealing. But if it sustained storm damage, I want to know more than whether the new flooring and kitchen look good.
What damage occurred? What work was completed? Were the necessary permits obtained and finalized? Was a substantial-damage determination issued? Were there earlier improvements or repairs that may affect what a future owner can do?
Some jurisdictions have cumulative substantial-improvement rules that count qualifying work over a specified period. The applicable period and calculation depend on the local rules. It would be a mistake to assume that every Pinellas municipality uses the same look-back period, or that a buyer automatically starts with a clean slate at closing.
This is where I want the permit history and municipal records reviewed, with questions directed to the building or floodplain officials who administer the rules for that particular address.
A buyer shouldn't discover after closing that a future renovation or repair may trigger requirements they never anticipated.
And remember, these floodplain rules aren't limited to direct waterfront homes. A property can be inland and still be located in a regulated flood hazard area.
What About Newer Elevated Construction?
For buyers who love the idea of waterfront living but have a lower tolerance for flood risk, newer elevated construction built to current floodplain standards may deserve serious consideration.
You may see homes where the main living area is elevated, with parking or other permitted uses below. That design can be an important distinction when comparing a newer home with an older, ground-level property.
It doesn't eliminate flood risk or make every elevated home equivalent. The home's actual elevation, construction, lower-level configuration and compliance still need to be evaluated.
But it can change the conversation about what kind of waterfront property fits a buyer's comfort level.
Get Insurance Quotes During Your Inspection Period
Insurance is another part of the waterfront budget that I don't want buyers to leave until the last minute.
When I'm working with buyers, I recommend obtaining homeowners and flood insurance quotes during the inspection period, not a few days before closing.
That gives them time to understand the cost of insuring the property while they may still have a contractual opportunity to decide whether to proceed.
If the premiums are substantially higher than expected, we need to know that before the applicable cancellation deadline.
Depending on the contract and its terms, a buyer who properly cancels within an available contingency period may be entitled to the return of their deposit. Waiting until that period has expired can put the deposit at risk.
Homeowners insurance and flood insurance are not the same thing. Standard homeowners policies generally do not cover flood damage, and a separate flood policy or appropriate endorsement may be needed. Wind or hurricane coverage, deductibles and exclusions also need to be reviewed for the specific property and policy.
Get the quotes early, review them with a qualified insurance professional and make sure the numbers work before you're committed to the purchase.
Waterfront Living Isn't One Lifestyle
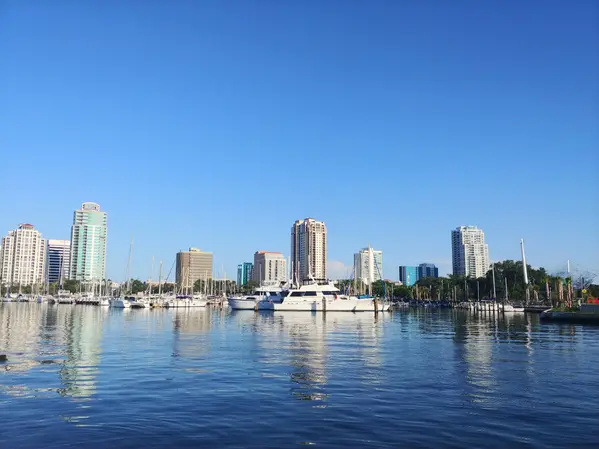
A home overlooking Tampa Bay, a property on Coffee Pot Bayou, a house along Boca Ciega Bay and a canal home in one of our beach communities can all offer something different.
One buyer may want to paddleboard at sunrise. Another wants a protected place to keep a boat. Someone else wants an unobstructed sunset view and has no intention of ever owning a boat.
That's why I start with the lifestyle rather than the listing.
And it's why the question isn't simply, “Do you want to live on the water?”
It's “What do you want to do when you get there?”
Before You Buy Waterfront in St. Pete, Know What Matters to You
The right waterfront property needs to work for more than the moment you first walk out onto the patio and see the view.
It needs to work for the way you'll use the water, the boat you own or hope to own, your comfort with flood risk, and the ongoing costs and responsibilities of ownership.
None of those considerations makes waterfront living less appealing. They simply help make sure you're buying the right waterfront property for the way you actually want to live.
Because the goal isn't simply to buy a house on the water.
It's to be able to enjoy living there once it's yours.
Frequently Asked Questions About Buying Waterfront Property in St. Pete
Does every waterfront home in St. Petersburg require flood insurance?
Not necessarily. The property's mapped flood zone, lender requirements and other applicable insurance requirements matter. Even where flood insurance isn't required, buyers should evaluate the risk and discuss coverage with an insurance professional. Standard homeowners insurance generally does not cover flooding.
Can I keep my boat at any home with a dock?
No. Water depth, bridge clearance, access routes, dock condition and lift capacity all need to work for your particular boat. Verify those details before purchasing.
What should I investigate when buying a waterfront home repaired after a hurricane?
Review the damage and repair history, permit records, any substantial-damage determination and the floodplain requirements enforced by the property's jurisdiction. Consider appropriate inspections by qualified professionals.
Is a flood zone the same as an evacuation zone?
No. Flood zones identify mapped flood hazards and are used for purposes that include floodplain regulation and insurance. Evacuation zones are used by emergency managers to identify areas that may need to evacuate because of hurricane-related hazards. A property should be checked for both.
Are newer elevated waterfront homes flood-proof?
No. Elevated construction can reduce certain flood exposures when properly designed and built, but buyers still need to evaluate the property's specific risks, construction and insurance needs.
About the Author
Terri Labrie is a St. Petersburg REALTOR® with Epique Realty and a member of the Epique Estates Luxury Division. A longtime St. Pete resident with nearly 20 years of prior paralegal experience, Terri brings an investigative approach to helping buyers and sellers understand not just the property, but the details that can affect a transaction and long-term ownership. She holds the ABR®, SRES®, SRS and PSA designations and serves clients throughout St. Petersburg and Pinellas County.

GET MORE INFORMATION